Monte Carlo Simulations in Regression Analysis: Applications in Multicollinearity and Autocorrelation Studies
DOI:
https://doi.org/10.33003/fjs-2026-1022-6081Keywords:
Monte Carlo Simulation, Multicollinearity, Autocorrelation, Ridge Regression, Generalized Least SquaresAbstract
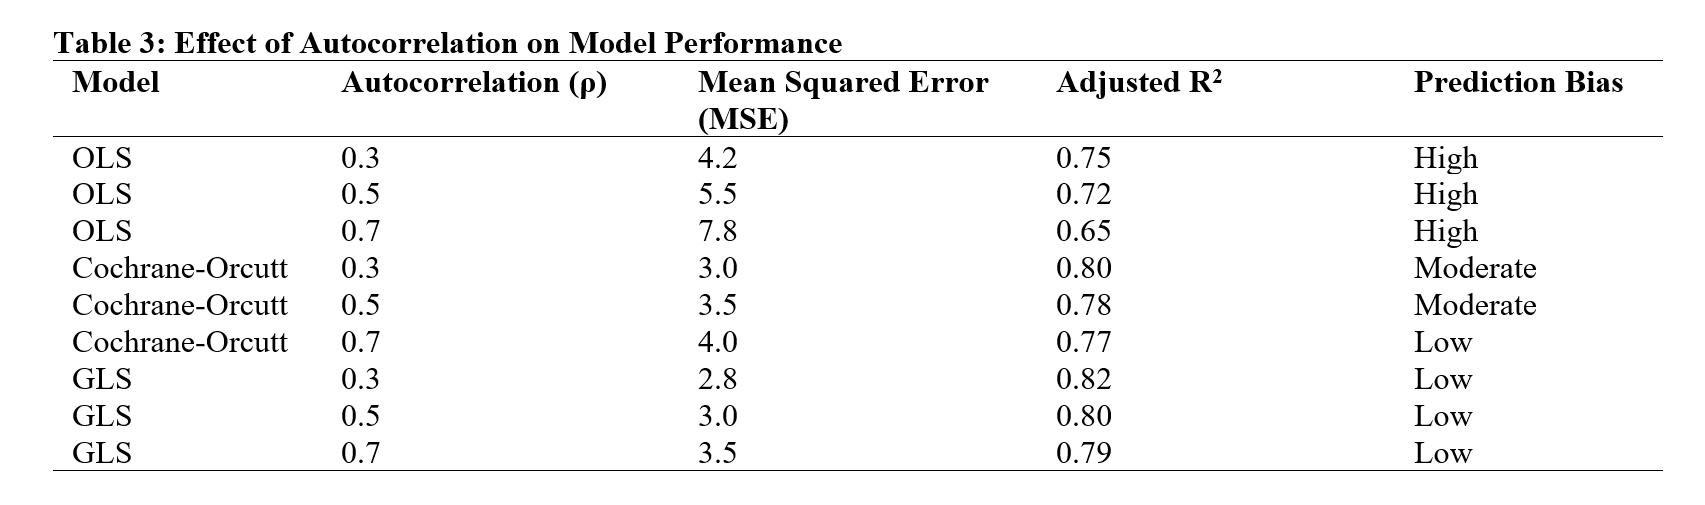
Monte Carlo simulations provide a controlled framework for evaluating regression estimators under multicollinearity and autocorrelation. This study evaluates Ordinary Least Squares (OLS), Ridge Regression, Cochrane-Orcutt and Generalized Least Squares (GLS) under varying degrees of predictor correlation and first-order autocorrelation. Predictor correlations of 0.7, 0.8 and 0.9 and autocorrelation parameter values of ρ = 0.5 and 0.7 are considered across the specified sample sizes, with 1,000 replications for each simulation condition. Model performance is evaluated using Mean Squared Error (MSE), Bias and Adjusted R2. The simulation results show how increasing predictor correlation affects coefficient stability and how increasing autocorrelation affects prediction performance. Ridge Regression provides more stable coefficient estimates under increased predictor correlation, while Cochrane-Orcutt and GLS improve performance under autocorrelated errors. The combined simulation results demonstrate differences in estimator performance when multicollinearity and autocorrelation occur simultaneously. The findings provide simulation-based evidence for interpreting regression estimator performance under the specified data conditions.
References
Adefegha, S. A. and Oboh, G. (2012). Inhibition of key enzymes linked to type 2 diabetes and sodium nitroprusside-induced Abdulkareem Tope R., Ganiyu Olayiwola S., Adullahi Babatunde H., & Oladokun Mamudat O. (2026). Econometric Modelling And ARIMA Forecasting of GDP Growth, Inflation Dynamiccs, and Exchange Rate volatility in Nigeria. FUDMA journal of sciences. Vol.10 NO 19, 178-186. https://doi.org/10.33003/fjs-2026-1019-5794
Agunbiade, A. (2012). Multicollinearity and autocorrelation in econometric models. Journal of Statistical Analysis.
Chatterjee, S., & Hadi, A. S. (2006). Regression analysis by example (4th ed.). Wiley.
Cochrane, D., & Orcutt, G. H. (1949). Application of least squares regression to relationships containing autocorrelated error terms. Journal of the American Statistical Association, 44(245), 32–61. https://doi.org/10.1080/01621459.1949.10483290
Dardick, W. R., & Harring, J. R. (2025). A novel numerical method for solving unknown statistical quantities in multivariate regression models. Journal of Educational and Behavioral Statistics, 50(1), 102–127. https://doi.org/10.3102/10769986241240083
Gilbert, J. B., & Miratrix, L. W. (2026). Multilevel metamodels: Enhancing inference, interpretability, and generalizability in Monte Carlo simulation studies. Multivariate Behavioral Research, 61(2), 287–310. https://doi.org/10.1080/00273171.2025.2586631
Greene, W. H. (2008). Econometric analysis (6th ed.). Pearson Prentice Hall.
Greifer, N., Worthington, S., Iacus, S., & King, G. (2025). Clarify: Simulation-based inference for regression models. The R Journal, 16(2), 154–174. https://doi.org/10.32614/RJ-2024-015
Gujarati, D. N. (2003). Basic econometrics (4th ed.). McGraw-Hill.
Gujarati, D. N., & Porter, D. C. (2009). Basic econometrics (5th ed.). McGraw-Hill Irwin.
Hammersley, J. M., & Handscomb, D. C. (1964). Monte Carlo methods. Methuen.
Hastie, T., Tibshirani, R., & Friedman, J. (2009). The elements of statistical learning: Data mining, inference, and prediction (2nd ed.). Springer.
Hoerl, A. E., & Kennard, R. W. (1970). Ridge regression: Biased estimation for nonorthogonal problems. Technometrics, 12(1), 55–67. https://doi.org/10.1080/00401706.1970.10488634
Maddala, G. S. (2002). Introduction to econometrics (3rd ed.). John Wiley & Sons.
Montgomery, D. C., Peck, E. A., & Vining, G. G. (2012). Introduction to linear regression analysis (5th ed.). John Wiley & Sons.
Paasche, H., Dega, S., Schrön, M., & Dietrich, P. (2025). Comprehensive data aleatory uncertainty propagation in regression random forest using a Monte Carlo approach: A struggle with incomplete data provision using a case study on probabilistic soil moisture regionalization. Frontiers in Environmental Science, 13, 1599320. https://doi.org/10.3389/fenvs.2025.1599320
Tibshirani, R. (1996). Regression shrinkage and selection via the lasso. Journal of the Royal Statistical Society: Series B (Methodological), 58(1), 267–288. https://doi.org/10.1111/j.2517-6161.1996.tb02080.x
Wold, H., Esbensen, K., & Geladi, P. (1987). Principal component analysis. Chemometrics and Intelligent Laboratory Systems, 2(1–3), 37–52. https://doi.org/10.1016/0169-7439(87)80084-9
Wooldridge, J. M. (2013). Introductory econometrics: A modern approach (5th ed.). Cengage Learning.
Downloads
Published
Issue
Section
Categories
License
Copyright (c) 2026 Oluwapamilerin Oyewole, Adekanmi Akinremi Oyewole, Oluwole Adegoke Nuga, Adekunle Oluseye Sangotola, Samson Oluwadamilare Busari

This work is licensed under a Creative Commons Attribution 4.0 International License.