Hybrid Principal Component-Based Estimators for Multicollinearity in Simultaneous Equation Models
DOI:
https://doi.org/10.33003/fjs-2026-1015-5867Keywords:
ulticollinearity, Principal Component Regression, Simultaneous Equation Models, Monte Carlo Simulation, Hybrid EstimatorsAbstract
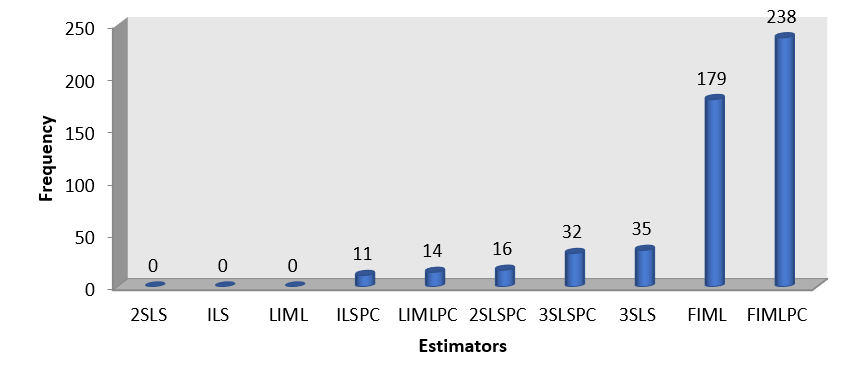
This study addresses the problem of multicollinearity in simultaneous equation models (SEMs) by proposing hybrid estimators that integrate Principal Component Analysis (PCA) with conventional estimation techniques. Multicollinearity, characterized by high correlations among explanatory variables, adversely affects the efficiency and stability of estimators such as Two-Stage Least Squares (2SLS), Three-Stage Least Squares (3SLS), and Full Information Maximum Likelihood (FIML). To mitigate this problem, correlated regressors are transformed into orthogonal principal components prior to estimation, leading to the PCR-based SEM estimators. The performance of both classical and hybrid estimators is evaluated through Monte Carlo simulations under varying levels of multicollinearity, sample sizes and error structures. Mean Squared Error (MSE) is used as the evaluation criterion. The results indicate that the hybrid PCR-FIML estimator consistently outperforms competing estimators in most experimental settings. Overall, incorporating PCA into SEM estimation improves predictive accuracy, reduces estimation variance, and enhances robustness in the presence of multicollinearity.
References
Alabi, O. O. and Oyejola, B. A. (2015). Assessment of Some Simultaneous Equation Estimation Techniques with Normal and Uniformly Distributed Exogenous Variables, Journal of Applied Mathematics, 6: 1902 – 1912. http://dx.doi.org/10.2015.611167.
Alabi, O. O. (2016). Assessment of Some Simultaneous Equation Estimation Techniques under Normally and Uniformly Correlated Exogenous Variables. Unpublished Ph.D. Thesis University of Ilorin, Ilorin, Nigeria.
Alabi, O. O. (2016). Assessment of Some Simultaneous Equation Estimation Techniques under Uniformly Distributed Exogenous Variables with Correlated Error Terms, Journal of the Nigeria Association of Mathematical Physics, 36, 203 – 214.
Alabi, O. O. (2019). Assessment of Estimation Techniques of Simultaneous Equation Model with Multicollinearity Problem under Normally and Uniformly Distributed Exogenous Variables, FUW Trends in Science and Technology Journal, 4(1), 103 – 117.
Alabi, R. E., Alabi, O. O., Ojo, O. O. and Fayose, T. S. (2025). Hybrid Estimators for Solving Multicollinearity in a Gaussian Linear Regression Model Based on Ridge – PCA Estimators. PSSN Conference Proceedings, 1 – 20. (to appear)
Aladesuyi, A., Ayinde, K. and Fayose, T. S. (2025): Assessing the Role of Significant Roots in Parameter Estimation of Linear Regression Models under Multicollinearity. Tech – Sphere Journal of Pure and Applied Sciences (TSJPAS), 2(1), 1 – 16. https://doi:/10.5281/zenodo.15470100.
Ayinde, K. (2007). Equation to Generate Normal Variates with Desired Intercorrelations Matrix. International Journal of Statistics and System, 2(2), 99 – 111.
Çankaya, S. and Eker, S. (2025). Ridge vs PCR in Regression with Multicollinearity. Turkish Journal of Agriculture – Food Science and Technology, 2(34), 101 – 127.
De Jong, S. and Kiers, H. A. L. (1992). Principal Covariates Regression: Part I. Chemometrics and Intelligent Laboratory Systems.
Fayose, T. S. and Ayinde, K. (2019). Different Forms Biasing Parameter for Generalized Ridge Regression Estimator. International Journal of Computer Applications, 181(37), 21–29. https://doi.org/10.5120/ijca2019918339.
Fayose, T. S., Ayinde K. and Alabi, O. O. (2023a). M Robust Weighted Ridge Estimator in Linear Regression Model. African Scientific Reports, 2(2), Article 123. https://doi.org/10.46481/ASR.2023.2.2.123.
Fayose, T. S., Ayinde K.; Alabi, O. O. and Bello, A. H. (2023b). Robust Weighted Ridge Regression Based on S – Estimator. African Scientific Reports, 2(3), Article 126. https://doi.org/10.46481/ASR.2023.2.3.126.
Johnson, T. L., Ayinde, K. and Oyejola, B. A. (2010). Effect of Correlations and Equation Identification Status on Estimators of a System of Simultaneous Equation Model, Electronic Journal of Applied Statistical Analysis, 3(2), 115 – 125.
Judge, G. G., Griffiths, W. E., Hill, R. C., Lutkepohl, H. and Lee, T. C. (1985). The Theory and Practice of Econometrics. 2nd Edition, New York, Wiley.
Leamer, E. E. (1978). Specification Searches: Adhoc Inference with Nonexperimental Data. New York, NY: John Wiley & Sons. 3), 371–380.
Olubusoye, E. A. (2001). The Consequences of the Violation of the Assumption of Zero Correlation between Pairs of Random Stochastic Terms used in Monte Carlo Experiments. An Unpublished Ph.D. Thesis submitted to the Department of Statistics, University of Ibadan, Nigeria.
Okeke, N. C., Olanrewaju, S. O. and Mohammed, Z. A. (2025). Robust Estimation in Simultaneous Equation Models: Addressing Multicollinearity and Heteroscedasticity through Adaptive Penalized GMM Techniques. African Journal of Mathematics and Statistics Studies, 8(3), 73–95. https://doi.org/10.52589/AJMSS-U1LHEDSZ
Schmidt, J. S. (2005). Econometrics, Published by McGraw – Hill International Edition.
Downloads
Published
Issue
Section
Categories
License
Copyright (c) 2026 Alademomi Aladesuyi, Olatayo Olusegun Alabi, Abimbola Hamidu Bello

This work is licensed under a Creative Commons Attribution 4.0 International License.