Econometric Modelling and ARIMA Forecasting of GDP Growth, Inflation Dynamics, and Exchange Rate Volatility in Nigeria
DOI:
https://doi.org/10.33003/fjs-2026-1019-5794Keywords:
Econometric Modelling, ARIMA Forecasting, GDP Growth, Inflation, Exchange-Rate Volatility, NigeriaAbstract
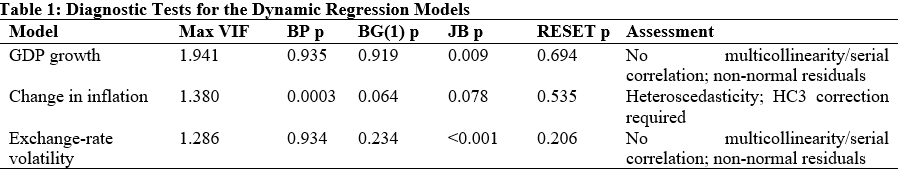
Macroeconomic forecasting is essential for economic planning, particularly in developing economies where growth instability, inflationary pressures, and exchange-rate uncertainty complicate decision-making. This study evaluates the adequacy and forecasting performance of econometric and Autoregressive Integrated Moving Average (ARIMA) models for Nigerian GDP growth, changes in inflation(DINF), and exchange-rate volatility (EXRV). Annual data covering 1990–2024 were analyzed. Dynamic regression models were estimated using 33 observations(1992–2024) to examine the relationships among lagged GDP growth, inflation changes, and exchange-rate volatility. Model adequacy was assessed using diagnostic tests for multicollinearity, heteroscedasticity, serial correlation, residual normality, and specification errors, with HC3 robust standard errors applied where necessary. The forecasting analysis employed ARIMA models estimated using the 1990–2019 training period and evaluated through fixed-origin out-of-sample validation for 2020–2024. Forecast accuracy was measured using MAE, RMSE, MAPE, and MASE. Results showed differences in model behaviour across indicators. The GDP growth regression displayed stronger within-model explanatory performance, with an adjusted R² of 0.327 and a significant HC3 robust joint test (p = 0.046); however, information criteria were interpreted only within individual model specifications and were not used for cross-model ranking. The selected ARIMA models were ARIMA(0,0,2) for GDP growth, ARIMA(0,1,0) with drift for inflation level forecasting, and ARIMA(0,0,0) for exchange-rate volatility. Validation results showed reduced forecast accuracy during periods of economic disruption. Forecasts for 2025–2029 are presented as conditional baseline projections with prediction intervals, reflecting uncertainty rather than guaranteed future outcomes. The study highlights the importance of combining diagnostic evaluation, forecast validation, and uncertainty assessment in Nigerian macroeconomic forecasting
References
Anifowose, A. D. (2021). Economic growth and exchange rate dynamics in Nigeria. Imo State University Business & Finance Journal, 12(1), 36–47.
Box, G. E. P., Jenkins, G. M., Reinsel, G. C., & Ljung, G. M. (2015). Time series analysis: Forecasting and control (5th ed.). Wiley.
Chatfield, C. (2000). Time-series forecasting. Chapman & Hall/CRC.
Diebold, F. X., & Mariano, R. S. (1995). Comparing predictive accuracy. Journal of Business & Economic Statistics, 13(3),
253–263. https://doi.org/10.1080/07350015.1995.10524599
Engle, R. F., & Granger, C. W. J. (1987). Co-integration and error correction: Representation, estimation, and testing. Econometrica, 55(2), 251–276. https://doi.org/10.2307/1913236
Hyndman, R. J., & Athanasopoulos, G. (2021). Forecasting: Principles and practice (3rd ed.). OTexts. https://otexts.com/fpp3/
Iheanachor, N., & Ozegbe, A. E. (2021). The consequences of exchange rate fluctuations on Nigeria’s economic performance: An autoregressive distributed lag (ARDL) approach. International Journal of Management, Economics and Social Sciences, 10(2–3), 68–87. https://doi.org/10.32327/IJMESS/10.2-3.2021.5
Makridakis, S., Spiliotis, E., & Assimakopoulos, V. (2018). The M4 competition: Results, findings, conclusion and way forward. International Journal of Forecasting, 34(4), 802–808. https://doi.org/10.1016/j.ijforecast.2018.06.001
Petropoulos, F., Apiletti, D., Assimakopoulos, V., Babai, M. Z., Barrow, D. K., Ben Taieb, S., Bergmeir, C., Bessa, R. J., Bijak, J., Boylan, J. E., Browell, J., Carnevale, C., Castle, J. L., Cirillo, P., Cramer, J. S., Davydenko, A., Fildes, R., Golinska-Dawson, P., Goodwin, P., ... Ziel, F. (2022). Forecasting: Theory and practice. International Journal of Forecasting, 38(3), 705–871. https://doi.org/10.1016/j.ijforecast.2021.11.001
Uche, E., & Nwamiri, S. I. (2022). Dynamic effects of exchange rate movements on productivity levels: New evidence from Nigeria based on NARDL. Journal of Development Policy and Practice, 7(1), 96–111. https://doi.org/10.1177/24551333211050704
Wooldridge, J. M. (2020). Introductory econometrics: A modern approach (7th ed.). Cengage Learning
Downloads
Published
Issue
Section
Categories
License
Copyright (c) 2026 Abdulkareem Tope Ridwanullahi, Ganiyu Olayiwola Suleiman, Abdullahi Babatunde Hassan, Adetunji Ramoni Adeoye, Oladotun Mamudat Olayemi

This work is licensed under a Creative Commons Attribution 4.0 International License.